

Snap Finance
by Snap Finance
4.8
- Safety
- 100% Safe
- Category
- Shopping
- Ratings
- 4.8
- Price
- Free
- Download
- 500.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
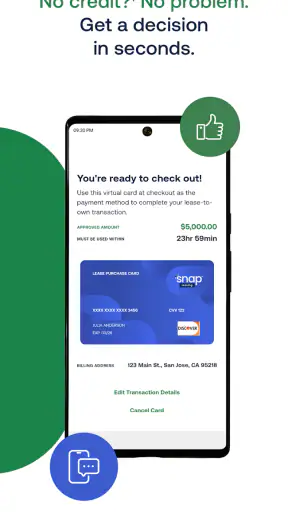
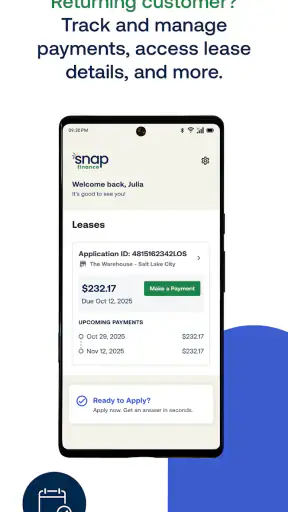
 Analysis by Getfullapps
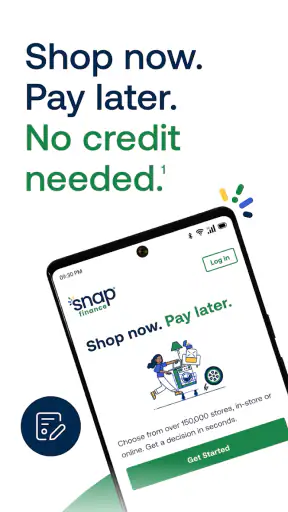
When an unexpected purchase cannot wait for a full payday, Snap Finance takes a very specific approach: it lets me shop now and spread the payment instead of relying on a traditional credit-card application. That single capability is the reason to look at this shopping app, but it is also the reason to use it carefully. “No credit needed” sounds simple; in practice, the useful question is whether the payment arrangement fits comfortably into my budget.
I reviewed it as a tool for planned purchases rather than as a general shopping destination. The app is free, comes from Snap Finance, and is rated for Everyone. It has built a sizable audience, with more than half a million installs and an average rating of 4.8 from roughly nine thousand ratings. Those numbers suggest that the basic experience works well for many people, although they do not remove the need to read the terms of any purchase before accepting it.
How the pay-later capability changes the shopping experience
The central idea is straightforward. Instead of paying the entire amount immediately, I can use Snap Finance during an eligible purchase and review a repayment arrangement. The practical benefit is cash-flow flexibility: a necessary item may become manageable when its cost is divided across scheduled payments.
That makes the app different from an ordinary retailer app. A retailer mainly helps me find an item, compare options, and complete checkout. Snap Finance is more concerned with how the purchase is paid for. It can therefore be useful when the product matters more than the timing of my available cash, but it is not a replacement for comparing the product itself or checking whether the total repayment is sensible.
The “no credit needed” positioning is especially relevant to shoppers who do not want a conventional credit check to be the only gateway to financing. Still, I would not treat that phrase as a promise that every application or every purchase will work the same way. Approval, payment amounts, and the final cost are the parts I would examine on screen before agreeing to anything.
My strongest advice is to separate two decisions that are easy to blend together: Can I obtain this item through the app? and Can I comfortably complete every payment? The first may be yes while the second is no. Snap Finance can make a large checkout amount feel smaller, but the obligation does not disappear; it is simply distributed over time.
What I would check before accepting an arrangement
I would begin by identifying the exact amount due at the start, the schedule of later payments, and the total amount that will leave my account. I would also look for any conditions attached to late or missed payments and confirm how the purchase is handled if the item is returned. These are not details I would leave for later, because the convenience of a quick checkout can make small print easier to overlook.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
A useful habit is to write the payment dates beside existing bills before completing the transaction. That simple step exposes a common weakness of pay-later tools: several individually modest commitments can become expensive when they overlap. Snap Finance is most helpful when I use it for one clearly planned purchase, not when I stack arrangements simply because each one looks affordable in isolation.
I would also compare the financed option with paying cash after waiting, using a normal credit card, or choosing a less expensive item. A financing app should solve a timing problem, not encourage me to stretch for a product that is outside my budget. If waiting a week or choosing a cheaper model removes the need for repayments, that may be the better financial decision.
How it feels in everyday use
The app’s value becomes clearer in a realistic situation. Imagine that a household appliance stops working shortly before payday. Replacing it may be urgent, while paying the entire amount immediately could leave too little money for groceries or transport. In that moment, I would use Snap Finance to explore whether the purchase can be divided into payments, then compare the full obligation with the cost of a basic replacement.
The important workflow is not simply tapping through checkout. I would first decide the maximum amount I can safely commit, then inspect the proposed schedule, and only afterward choose the item. Doing it in the opposite order makes it easier to become attached to a more expensive product before seeing what the commitment means for the rest of the month.
For a planned purchase, I would use the app as a budgeting checkpoint. I might save the product details elsewhere, calculate what the recurring payment does to my monthly spending, and return only if the numbers still work. That extra pause reduces the temptation created by seeing a smaller periodic amount instead of the complete cost.
The latest listed version is 2.2.11632, and the app supports Android 7.0 or later. That broad compatibility is useful if I am using an older Android phone, although I would still keep the operating system and the app updated where possible. A finance-related app is not something I would install from an unofficial source or use on a device I do not control.
The best fit: urgent, necessary purchases with a clear repayment plan
In my view, the strongest use case is a necessary purchase that cannot reasonably wait and has a repayment plan I can already accommodate. A broken essential appliance, required household equipment, or another practical replacement is easier to justify than an impulse purchase made because the initial checkout amount looks lower.
This is also where the app can be more useful than a conventional credit card for someone who does not want to depend on an established credit history. The application may offer an alternative route to arranging payment, while the user retains responsibility for checking the complete cost and meeting every scheduled obligation.
I would be more cautious with fashion, entertainment, upgrades, and other purchases that are pleasant but optional. Those items can still be financed, but the trade-off is harder to defend if the repayments continue after the excitement has faded. The convenience is real; so is the risk of turning a want into a recurring bill.
Another good scenario is a purchase where the lower-cost alternative would fail quickly or create more expense later. Even then, I would compare warranties, return conditions, and product quality separately. Financing the wrong item does not make it a good purchase. Snap Finance addresses payment timing, not product reliability.
The trade-offs hidden behind a smaller payment
The biggest limitation is psychological rather than technical: dividing a price can make an expensive purchase feel less expensive. I find that the safest way to counter this is to look at the total repayment first and the periodic amount second. If the full figure changes my mind, that is useful information, not an inconvenience.
There is also a planning burden. I would need to remember the schedule, keep enough money available on the relevant dates, and respond promptly if anything changes. Someone with irregular income may find a fixed repayment arrangement stressful even when the initial approval is easy. In that situation, saving first or using a more flexible payment method could be preferable.
The app should not be treated as an automatic solution for damaged credit or limited income. Avoiding a traditional credit requirement may open a door, but it does not make repayment risk-free. If I am already struggling with existing bills, adding another obligation is unlikely to improve the situation. The responsible choice may be to delay the purchase, seek a lower-cost option, or ask the retailer about alternatives.
Compared with a credit card, the advantage is a more purchase-focused route that may suit someone who does not want to use revolving credit. The disadvantage is that a credit card can sometimes offer broader spending flexibility or a familiar account-management system, depending on the user’s circumstances. Compared with paying cash, Snap Finance offers speed but removes the simplicity of being finished at checkout. Compared with saving, it provides the item sooner but creates a future commitment.
Those comparisons matter because there is no universally best payment method. I would choose Snap Finance when the timing problem is genuine and the repayment plan is comfortably visible in my budget. I would choose cash when I can wait, and I would avoid financing when the purchase depends on hoping that future income will somehow be higher.
Small habits that make the app safer to use
One practical habit is to create a “payment map” before checkout. I would list the proposed Snap Finance payment alongside rent, utilities, subscriptions, and other scheduled expenses. This reveals whether the arrangement is affordable during an ordinary month, not only during the week when the purchase feels urgent.
A second habit is to keep the purchase confirmation and repayment details together. I would save the relevant information in a place I can revisit, rather than assuming I will remember the dates. This is especially useful when the item is bought during a stressful situation, because urgency makes it easy to forget the exact commitment.
A third is to test the decision against a cheaper substitute. If a basic version solves the same problem without financing, I would calculate both options before applying. The more expensive product may still be worthwhile, but the comparison prevents the payment plan from deciding the product choice by itself.
I would also avoid using the app as a bridge between multiple paydays. If the only way to complete the arrangement is to postpone another bill or rely on another financing product, the purchase is not comfortably affordable. That is the point at which the convenience becomes a warning sign.
Who will benefit most, and who should skip it
Snap Finance is best suited to an adult shopper who needs a purchase now, does not want a conventional credit-based route, and can clearly handle the scheduled payments. It may also help someone who wants to keep an emergency cash reserve intact for a short period, provided the repayment plan does not consume that reserve later.
I would recommend caution for anyone with unpredictable income, several existing pay-later commitments, or a habit of judging affordability by the smallest displayed payment. The app is also a poor fit for someone who has not compared the total cost with cash, a lower-priced item, or waiting. In those cases, the tool may make the checkout easier while making the overall financial decision worse.
The Everyone content rating makes the app broadly accessible from a store perspective, but that should not be confused with financial suitability for every household. A person can be old enough to use the app and still be better off avoiding a new payment obligation. The right question is not whether the app is easy to access; it is whether the purchase remains sensible after the excitement of getting it today has passed.
After using it as a focused shopping-finance tool, I see Snap Finance as useful but deliberately narrow. Its strength is giving eligible shoppers another way to manage the timing of a purchase, particularly when traditional credit is not the preferred route. Its weakness is that the same flexibility can encourage overbuying or make a strained budget look healthier than it is.
My recommendation is simple: use it for a necessary, planned purchase, inspect the total repayment, place every payment date into your budget, and compare the result with cash and cheaper alternatives. If those checks still leave the arrangement comfortable, the free app from Snap Finance can be a practical option. If they do not, no amount of checkout convenience makes the purchase worth carrying.
Pros
- Quick application process with decisions often available within minutes.
- May help finance essential purchases when traditional credit is limited.
- Clear payment schedules make installment amounts easier to plan.
- Available at participating retailers for convenient point-of-sale financing.
- Online account access helps track payments and remaining balance.
Cons
- Approval does not guarantee low interest or favorable total repayment costs.
- Late payments may lead to fees and could negatively affect your credit profile.
- Financing options and limits vary significantly by applicant and retailer.
- Some purchases may require a down payment or additional upfront costs.
- Automatic payment requirements may be inconvenient for some customers.
FAQs for Snap Finance
What is Snap Finance, and how does it work?
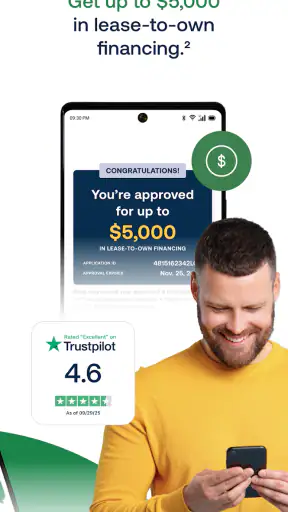
Snap Finance is a lease-to-own financing service that may help eligible shoppers purchase products when traditional credit is unavailable or insufficient. After submitting an application, you receive a decision based on the information provided and, if approved, can use the offer with participating merchants. Carefully review the payment schedule, total cost, renewal terms, and purchase options before accepting.
Does using Snap Finance require a good credit score?
Snap Finance is generally marketed toward consumers who may have limited or less-than-perfect credit, so approval is not based solely on having an excellent credit score. However, approval is never guaranteed, and the company may consider several factors, including your application details and ability to make payments. Applying may also involve identity and income verification.
How much does Snap Finance really cost?
The amount you ultimately pay can be higher than the product’s cash price because lease-to-own agreements may include fees, scheduled payments, and an early purchase option. The exact cost depends on the merchant, purchase amount, agreement, and payment plan. Before signing, compare the total of all payments with the cash price and read every disclosure carefully.
Can I use Snap Finance for any purchase or at any store?
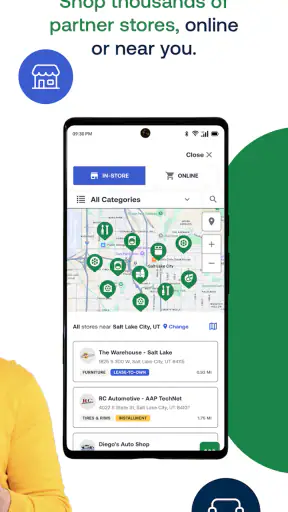
No. Snap Finance can generally be used only for qualifying purchases at participating merchants and for products that meet the provider’s requirements. Availability may vary by location, retailer, product category, and approved spending amount. The app or application process may help you identify available offers, but you should confirm acceptance with the specific merchant before planning your purchase.
What happens if I miss a Snap Finance payment?
Missing a payment can lead to late fees, unsuccessful payment charges, collection activity, or other consequences described in your agreement. It may also affect your ability to use the service again. If you expect difficulty making a payment, contact Snap Finance promptly and review the available support options. Never assume that returning the product automatically cancels the agreement or remaining balance.

Snap Finance
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via mobile@snapfinance.com, visit https://snapfinance.com, or review their https://snapfinance.com/legal/privacy.










